
42% Name manual reconciliation as their biggest pain
Not as an irritation. As the thing most responsible for errors and delay in financial reporting.
Financial services · India & South Asia
That gap is where thirty percent of your finance team's week goes.
industry efficiency ratio, meaning that share of revenue is consumed by operating expense.
Source: FDIC Quarterly Banking Profile
In India
Platforms in this market
Rules that apply here
We read the rule before the call. It is the cheapest way to prove we did the work.
What is happening
Not as an irritation. As the thing most responsible for errors and delay in financial reporting.
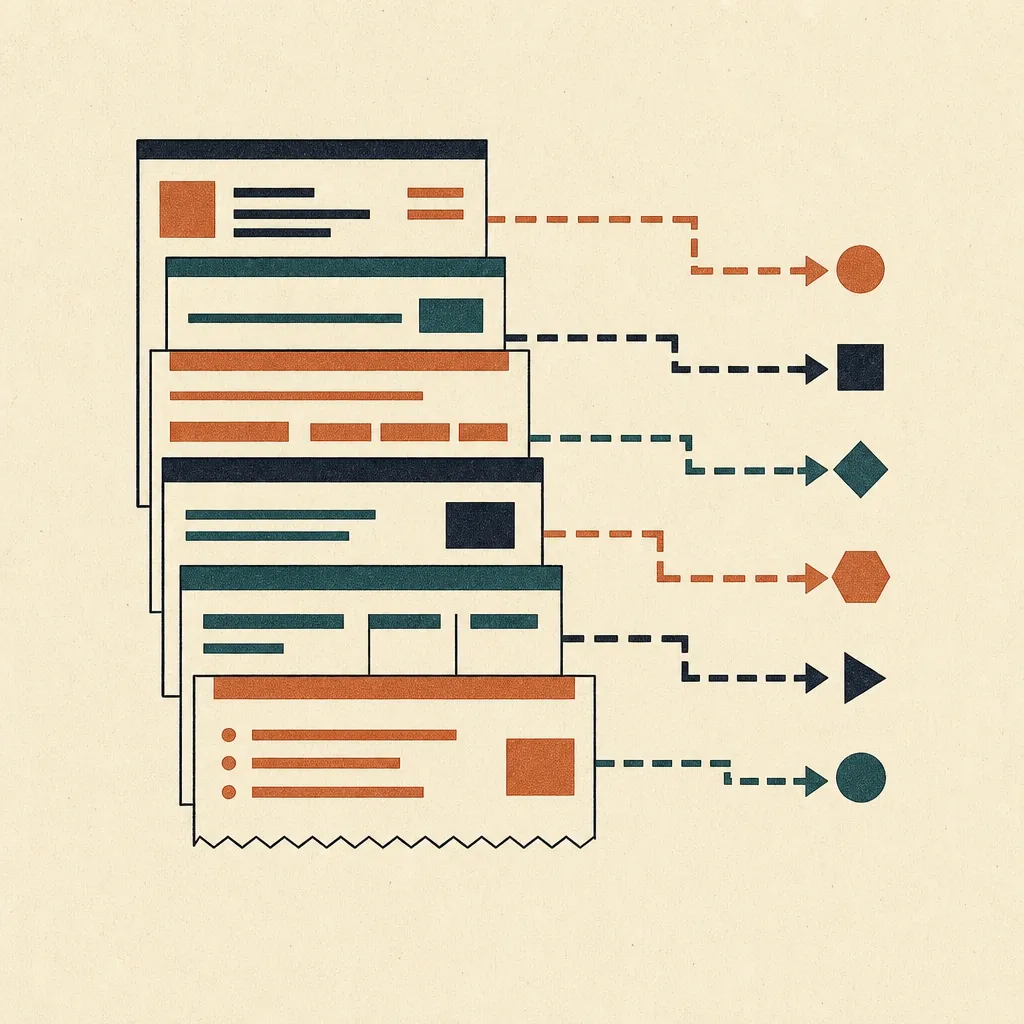
Bank statements that do not match. Part payments. Remittances with no reference. Transfers between your own entities. And ACH, wire, card, RTP and FedNow all running at once.
The tools that solve this exist. They are sold to institutions ten times your size, and the licence alone exceeds what the problem costs you — until you count the risk.
One person knows why that account always breaks by a few thousand at month end. When they leave, the knowledge does.
However hard, whatever it is
We wrote this page about matching. If yours is onboarding, collections or a report the regulator keeps rejecting, the method does not change.
 01
Days where the work happens, not a workshop in a meeting room. We watch the job get done and write down the shortcuts nobody wrote down.
 02
Your data, your rules, your vendors and their documentation, and the published research on your sector. We report what is actually in there.
 03
Not which tool fixes this. What is actually causing it, taken apart until we reach the piece that cannot be divided further.
 04
Weeks, not quarters. By this point we are not guessing what to build, and guessing is the thing that makes projects long.
Where we sit
What you get
Built new for you — none of this exists in your stack today
What you already run — unchanged, and still yours
If your core can print it, we can read it. A green-screen terminal, a nightly fixed-width file, a scanned mandate. We have built against all three.
 No API
 No documentation
 A terminal from 1994
 It arrives as paper
 The vendor said no
 It reports nothing
Not a list of limits. Name yours on the call.
And once we can reach it, a model can read it. Most of the value here is in the sources nobody ever structured — the note, the letter, the screen.
Intelligence, plumbed in
Underneath that: a connector to the core, one agreed meaning for each field, and a test set of real files we score against.
How we make AI survive real data Connectors
 A semantic layer
 Evals you can check
What changes
 Days to hours
Matching rules learned from your own history, exceptions ranked by value and age, and a queue rather than a spreadsheet.
 Exceptions
With the probable cause attached, drawn from how that account has broken before.
 Audit
Who matched what, when, and on what basis. The thing auditors actually ask for.
Who this is for
 Chief Financial Officer
 Head of Operations
 Financial Controller
 Head of Internal Audit
 Chief Risk Officer
Straight answers
Core system modules reconcile what is inside the core system. The breaks that cost you sit between systems: the bank statement, the payment gateway, the ledger, the partner file. Each one uses a different format and a different reference. That translation is the work.
There is machine learning in the matching, but that is an implementation detail rather than the pitch. The value is in handling your specific formats, your specific exceptions and your specific approval chain.
Financial data stays inside your infrastructure or a region you nominate. Access is role-scoped and logged per record, and we sign whatever data processing agreement your compliance team requires before access.
It reads, it never posts. Extractions are scored against files your team already processed. Anything written back waits for a maker and a checker.
For banking & lending that means the RBI, CKYC, the Account Aggregator framework and the DPDP Act 2023. We read the rule before the call, so the first meeting is about your operation rather than about us catching up.
What you already run stays where it is. Around it we build software, hardware and the process itself. Here that means a loan file that assembles itself from what you already hold.
See everything we build Software
 Hardware
 Ways of working
 Whole ventures
Honest about the numbers
We have not localised it, because a number nobody can check is worth less than a real one plus this sentence. The pattern travels. The size of it in your market is a question for the call.
Same industry, other markets