
A combined ratio above one hundred means underwriting lost money
Our combined ratio is above 100. How much of that is operational rather than underwriting?
Figures and rules on this page apply to
United States
Working somewhere else? The shape of the problem usually travels. The deadlines do not.
What this looks like
The underwriting review examines pricing and exposure, which is correct and necessary. What it does not examine is the rest. A broker's bordereau arrived with the columns moved again, three people spent a week on it, and the statement it produced drew eleven queries. None of that is an underwriting decision, and all of it is in the ratio.
The numbers
Every figure here is someone else’s. Check them.
- 103.7%industry combined ratio at the most recent half-year, meaning an underwriting loss
- 104.1%the full-year figure two years earlier, which had worsened by 6.3 points
- $1.09Tpolicyholders' surplus, which is why the industry absorbs this rather than repricing overnight
Why it happens
It is not a people problem.
A combined ratio adds two very different things: what you paid out and what it cost you to operate. The first is underwriting and gets forensic attention. The second is settlement work, and settlement work is mostly the reconciling of documents that arrive in whatever shape the sender chose. Nobody reviews it because it is not a decision, it is a cost of being connected to other firms.
Why your current software has not fixed it
Because it was never built to.
Your policy administration platform is authoritative about the policy. It cannot be authoritative about a spreadsheet a broker emailed, because that spreadsheet changes shape whenever the broker's own system does. Mapping it lives in a script somebody wrote, and the script breaks quietly the first time a column moves. That is not a product gap anybody can close for you. The formats belong to the firms you trade with.
Intelligence, plumbed in
A bordereau with the columns moved is still readable. A script is what breaks.
The build is a reader for any bordereau layout, a break list that names the policy, and a statement brokers can query themselves. Underneath it: a connector, one agreed meaning per field, and a test set scored on your own records.
How we make AI survive real data-
 Connectors
-
 A semantic layer
-
 Evals you can check
However hard, whatever it is
Bordereaux are one example. Bring the messier one.
We wrote this up because NAIC publishes the ratio. If yours is claims triage, broker onboarding or a regulatory return, the approach holds.
-
 01
We sit with you
Days where the work happens, not a workshop in a meeting room. We watch the job get done and write down the shortcuts nobody wrote down.
-
 02
We read everything
Your data, your rules, your vendors and their documentation, and the published research on your sector. We report what is actually in there.
-
 03
We break it to first principles
Not which tool fixes this. What is actually causing it, taken apart until we reach the piece that cannot be divided further.
-
 04
Then we build
Weeks, not quarters. By this point we are not guessing what to build, and guessing is the thing that makes projects long.
What we build
Specific enough to argue with.
Four mechanisms, not four features. Each one is a thing that happens on its own, every day, whether or not anyone remembers to run it.
-
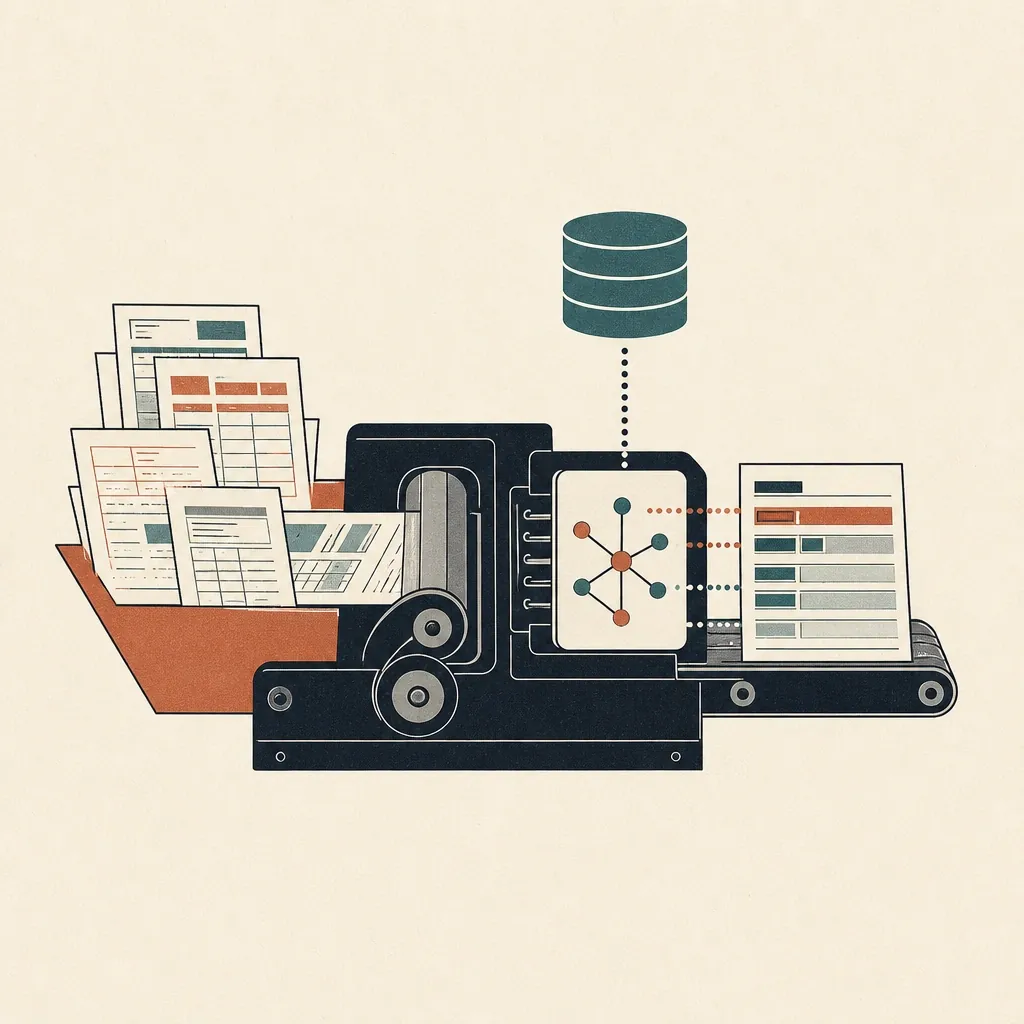
A reader that takes a bordereau however it is laid out. The mapping lives in a semantic layer, not in a script nobody owns.
-
A break list that names the policy and the probable cause, not just the unmatched total.
-
A commission statement a broker can query themselves, which removes most of the queries rather than answering them faster.
-
Accuracy reported per broker, so the one relationship that is actually costing you is visible instead of averaged away.
How you would know it worked
Numbers in your own reporting, not ours.
- Expense side of the combined ratio, tracked separately from loss experience.
- Days to settle a bordereau from receipt, and how many of those days are reconciliation.
- Broker queries per statement, which is the cleanest proxy for whether the numbers are trusted.
Straight answers
Where a model is involved, it is scored against your own records first. Accuracy per source, not one flattering average.
The questions this raises
-
Is this not just better underwriting?
No, and that is the point. Underwriting gets reviewed already. The expense half of the ratio rarely does, because it is nobody's decision and therefore nobody's agenda item.
-
Our brokers will not change their format.
They should not have to. The mapping is our problem, and holding it in a layer rather than a script is what stops it breaking when a column moves.
-
Does anything post to the ledger automatically?
Nothing posts without a checker. We read, match and propose; a person approves. That is the same discipline your controls already require.
-
We are outside the US. Do these ratios apply?
The figures are US property and casualty data and we say so. The mechanism is identical wherever bordereaux arrive as spreadsheets, which is most places.
Where the figures come from
We did not make these up, and you should not take our word for them.
Every partner sends a different shape
The format belongs to them. The cost lands on you.
Documents arrive from outside in whatever shape the sender chose, and the sender changes it whenever their own system does. No vendor can ship this. The set of formats is specific to who you trade with, which is why it ends up as a script nobody owns.
- Agriculture & foodThe traceability deadline moved to 2028, and nothing else changed
- Banking & lendingFifty-five cents of every revenue dollar goes to running the bank
- HospitalityThe roster was set last Tuesday. The covers were not
- RetailShrink went from 1.4 to 1.6 percent, and the till already knew where
- Supply chainThe official inventory number arrives six weeks after the month it describes
Bordereaux, carrier files, supplier invoices, delivery notes. Whatever arrives in your inbox in nine shapes is the same job.Send us the messiest one you have.
Half the ratio is underwriting. The other half is the cost of settling.
The build is a reader for any bordereau layout, a break list that names the policy, and a statement brokers can query themselves.
See everything we build-
 Software
-
 Hardware
-
 Ways of working
-
 Whole ventures
Is this happening to you? Tell us the size of it.
Twenty minutes. We will tell you honestly whether the numbers justify doing anything about it.